Should You Wait for Lower Rates to Buy a Home? Here’s What the Math Says
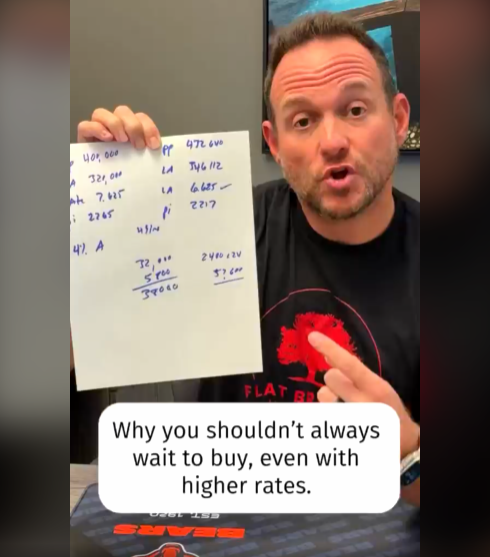
A lot of buyers are sitting on the sidelines right now, waiting for mortgage rates to come down before they make a move. It feels like the safe choice. But when you run the numbers, waiting can cost you more than the rate drop saves you.
Let’s walk through a real example.
The Scenario: Buying Today
Say you want to buy a $400,000 home and put 20% down.
- Purchase price: $400,000
- Down payment (20%): $80,000
- Loan amount: $320,000
- Interest rate: 7.625%
- Monthly principal and interest: about $2,265
That payment feels high, so the instinct is to wait it out.
The Scenario: Waiting Two Years
Home values don’t stand still while you wait. Over the last 10 to 15 years, many markets have seen appreciation of 3% to 5% per year. Let’s use the middle of that range, 4%.
After two years of 4% appreciation, that same $400,000 house is worth about $432,640. You’re now paying $32,640 more for the exact same home.
Here’s how that changes your numbers:
- Purchase price: $432,640
- Down payment (20%): $86,528, which is $6,528 more cash out of pocket
- Loan amount: $346,112, so you’re borrowing about $26,000 more
Now let’s assume the best case for waiting: rates fall a full point, to 6.625%. Your new monthly principal and interest comes to about $2,216.
So yes, waiting saved you money on the monthly payment. About $49 a month.
What Waiting Actually Cost You
Here’s the side-by-side:
| Buy Today | Wait 2 Years | |
|---|---|---|
| Home price | $400,000 | $432,640 |
| Down payment | $80,000 | $86,528 |
| Loan amount | $320,000 | $346,112 |
| Interest rate | 7.625% | 6.625% |
| Monthly P&I | ~$2,265 | ~$2,216 |
That $49 a month in savings comes with a much bigger price tag:
You missed out on $32,640 in appreciation. If you’d bought today, that increase in value would have been your equity, not the seller’s.
You missed out on about $6,000 in loan paydown. Two years of payments on the original loan would have knocked roughly $6,000 off your principal balance.
Add those together, and waiting cost you about $38,600 in equity, all to save $49 a month.
And You Still Had to Live Somewhere
This is the part people forget. You don’t stop paying for housing while you wait. If you’re renting at $2,400 a month, two years of rent adds up to $57,600, and none of it builds equity.
What If Rates Do Drop?
If rates fall after you buy, you can look at refinancing into the lower rate. You can change your rate later. You can’t go back and buy the house at the old price.
The Bottom Line
Waiting for rates to drop can feel like the cautious move, but it often means paying more for the house, bringing more cash to closing, borrowing more, and giving up equity you could have been building the whole time.
Every situation is different, and appreciation isn’t guaranteed in every market or every year. But before you decide to wait, it’s worth sitting down and running your own numbers.
Thinking about buying? Reach out and we’ll walk through the math for your situation.